2026 IRS 401(k) & Retirement Limit Increases
More room to save for retirement – with smart tax advantages.
የቦ ኮሚኒኬሽን ኔትወርክ
ለ25 ዓመታት በላይ – ትርጉም፣ ፓስፖርት፣ ቪዛ፣ ታክስ፣ ትራቨል፣ ውክልና እና ሌሎችም ከ200 በላይ አገልግሎቶች በአንድ ቦታ!
- ✔ ትርጉም እና ሎካሊዜሽን – Ethiotrans.com
- ✔ ታክስ አገልግሎት – YebboTax.com
- ✔ ቪዛ፣ ትሬቫል እና ፓስፖርት
- ✔ ውክልና አገልግሎት
- ✔ ፎቶ እና ቪዲዮ አገልግሎት
- ✔ ኦንላይን እቃ ሽያጭ
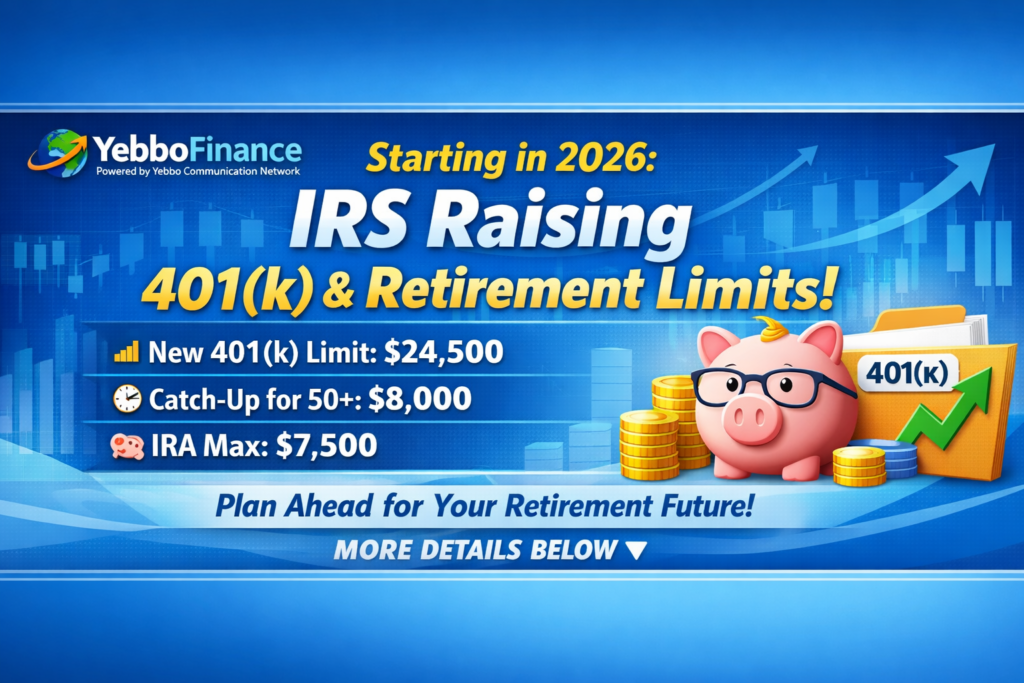
Quick Snapshot: New 2026 Retirement Limits
The IRS has officially announced higher contribution limits for 2026. Here are the key numbers most savers care about:
Why Is the IRS Raising Retirement Limits?
Retirement is getting more expensive and lasting longer. Housing, food, and health care costs continue to rise, and many Americans do not start saving early enough. By increasing contribution limits, the IRS is giving workers and business owners more room to save in tax-advantaged accounts.
These changes are also part of SECURE Act 2.0, a law designed to modernize retirement plans, expand access to small businesses, and encourage people in their 50s and 60s to boost savings during their peak earning years.
የጡረታ ሕይወት ዛሬ ከዚህ በፊት በነበረው ይልቅ ውድ እና ረዥም ሆኗል። ቤት፣ ምግብ፣ የጤና አገልግሎት ዋጋዎች ከፍ ብለው ስለሚሄዱ ሰዎች በጊዜው ብዙ ጊዜ ማስቀመጥ አያስጀምሩም። በዚህ ምክንያት አይ.አር.ኤስ (IRS) የ401(k) እና የሌሎች የጡረታ መረጃዎች ገደብ በመጨመር የገቢ ታክስ ቅናሽ በማድረግ ብዙ ገንዘብ እንዲቆሙ እድል ታስቀምጣለች።
How the New Limits Affect Different Savers
1. Employees Under Age 50
If you are under 50, your maximum 401(k)/403(b)/457/TSP contribution jumps to $24,500 in 2026. Even if you cannot max it out, increasing your monthly contribution by a small amount (for example, $50–$200 more per month) can add tens of thousands of dollars to your future retirement balance.
2. Ages 50+
Once you turn 50, you can make catch-up contributions. In 2026, the catch-up limit for most workplace plans rises to $8,000. That means you can contribute up to $32,500 total into your 401(k)/403(b)/457/TSP each year.
3. Ages 60–63
Thanks to SECURE 2.0, workers aged 60–63 keep an even higher catch-up band of $11,250 for many employer plans. This creates a powerful “final push” window where you can supercharge retirement savings.
4. IRA Savers
For 2026, the total you can put into a Traditional or Roth IRA is $7,500, plus an extra $1,100 catch-up if you are 50 or older (subject to income limits for deductions/eligibility).
How to Prepare Before 2026
- Review your current contributions – Check if you are contributing a flat dollar amount or a percentage of pay.
- Turn on auto-increase – Many 401(k) plans allow you to automatically increase contributions annually.
- Ask about employer match – Make sure you are at least contributing enough to capture 100% of any match.
- Self-employed? – Consider a Solo 401(k), SEP IRA, or SIMPLE plan to take advantage of higher limits.
- Coordinate 401(k) + IRA – Use both workplace and IRA accounts, where allowed, for multiple tax strategies.
Video Explainer (Optional)
You can embed a short YebboFinance video here breaking down the new IRS limits in 2–3 minutes. Replace the YouTube link below with your own channel’s video URL.